No. Under IRC 408m, IRA-owned precious metals must be held by a qualified trustee at an IRS-approved depository. Storing IRA metals at home triggers three simultaneous penalties: ordinary income tax on the full IRA value, a 10 percent early withdrawal penalty (if under 59-1/2), and a 15 percent IRC 4975 prohibited transaction excise tax. The U.S. Tax Court has never upheld a home storage precious metals IRA structure. The compliant alternative -- a 401k rollover or trustee-to-trustee transfer into a self-directed IRA -- lets you hold physical gold legally.
- A home storage precious metals IRA triggers a deemed distribution on day one -- IRC 408m forces the full IRA balance into ordinary income immediately.
- Three penalties stack simultaneously: income tax at your marginal rate + 10 percent early withdrawal penalty + 15 percent IRC 4975 excise tax -- often exceeding 60 percent of account value.
- No LLC, checkbook IRA, or trustee structure can cure the prohibited transaction created by home possession of IRA metals.
- A $200,000 IRA home-stored by a 52-year-old in the 32 percent bracket faces over $114,000 in combined tax liability.
- IRS-approved depositories -- Delaware Depository, Brinks Global Services, IDS -- provide compliant segregated or commingled storage for $100-$300/year.
- A compliant SDIRA funded via 401k rollover or trustee-to-trustee transfer can hold physical gold at an approved facility -- legally and tax-efficiently.
What Is a Home Storage Precious Metals IRA?
A home storage precious metals IRA markets an account configuration the IRS classifies as a deemed distribution on day one. Despite aggressive marketing by promoters, no IRS ruling, revenue procedure, or private letter ruling has ever approved a structure where the IRA owner stores metals at home. Every promoter of such schemes has faced IRS enforcement actions.
Home storage promoters — who have faced IRS enforcement actions resulting in seven-figure tax assessments and client litigation — claim that forming a limited liability company (LLC) owned by your IRA would allow you to serve as the LLC manager and store metals in a home safe. This structure, called a checkbook IRA, has been rejected in every published U.S. Tax Court decision addressing the scheme, including McNulty (2021) and Keystone (2017).
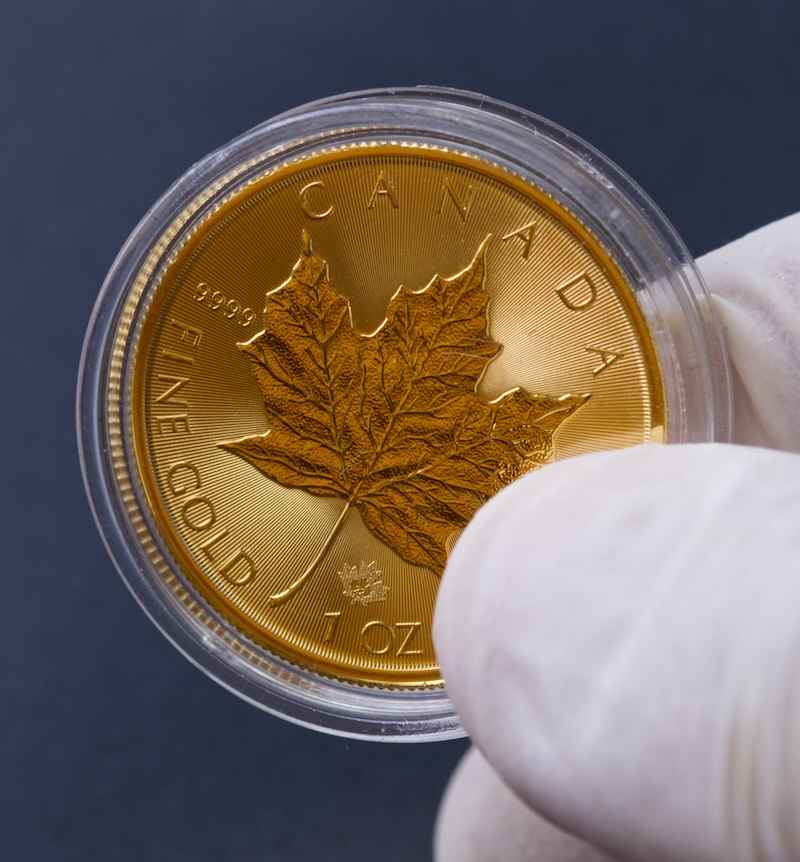
A compliant self-directed precious metals IRA holds IRA-eligible metals — gold at minimum .995 fine (e.g., American Gold Eagles, Canadian Maple Leafs, PAMP Suisse bars), silver at .999 fine, and platinum or palladium at .9995 fine — at an IRS-approved depository such as Delaware Depository Service Company, Brinks Global Services, or International Depository Services (IDS), held in segregated or commingled storage under the qualified custodian's name for the benefit of the IRA account. Numismatic (collectible) coins and metals below minimum fineness do not qualify, regardless of where they are stored.
Why the IRS Prohibits Home Storage of IRA Metals
A compliant precious metals IRA routes all physical metals exclusively through a qualified trustee or custodian -- barring the account holder, any related party, and any entity the holder controls from taking physical possession, as required by IRC 408m. IRC 408m classifies IRA-held physical metals as collectibles -- forcing immediate distribution -- unless those metals meet fineness thresholds AND sit at a qualified depository.
A home storage precious metals IRA violates IRC 408m the moment the account owner, a disqualified person, or any personally controlled LLC takes physical possession -- including storage in a home safe or a safe deposit box held in the owner's name. The IRS reinforced this position in McNulty v. Commissioner, T.C. Memo. 2021-43 (U.S. Tax Court), where Judge Goeke ruled that Andrew and Donna McNulty's home-stored American Eagle coins -- purchased through a self-directed IRA-owned LLC called Green Hill Holdings -- constituted a $411,427 taxable distribution.
The applicable penalty framework under IRC §4975 treats such arrangements as prohibited transactions, subject to a 15% excise tax on the transaction amount — separate from ordinary income tax and the 10% early withdrawal penalty. A disqualified person under IRC §4975(e)(2) includes the IRA owner, their spouse, ancestors, lineal descendants, and any entity in which the IRA owner holds a 50% or greater interest.
IRS enforcement actions against home storage promoters — including formal summons proceedings and injunctions against multiple scheme operators since 2015 — have resulted in assessments exceeding $50 million in back taxes, penalties, and excise taxes across documented cases. The IRS Office of Chief Counsel has issued multiple memoranda confirming that no LLC structure can cure the prohibited transaction created by home possession of IRA metals.
The LLC Checkbook IRA Myth: Why It Still Fails IRS Scrutiny
Promoters frequently market an LLC checkbook IRA as a legal workaround for home storage — but the IRS and Tax Court have consistently ruled these structures trigger prohibited transactions under IRC §4975. The typical scheme works like this: your IRA forms an LLC, you serve as the LLC manager, the LLC opens a bank account (the checkbook), and you purchase metals and store them in a home safe.
This structure fails for three reasons:
- Self-dealing: The IRA owner acting as LLC manager and physically controlling IRA assets constitutes self-dealing under IRC §4975(c)(1)(E).
- Prohibited transaction: Transferring IRA assets to an entity controlled by the IRA owner is a prohibited transaction under IRC §4975(c)(1)(D).
- Deemed distribution: Physical possession by the IRA owner or a controlled entity triggers a deemed distribution under IRC §408(m)(3)(B), making the entire IRA balance taxable.
In McNulty v. Commissioner (T.C. Memo. 2021-43), the taxpayer formed an LLC, purchased American Eagle gold coins through the LLC, and stored them in a home safe. The Tax Court ruled the coins were a taxable distribution in the year of purchase. The taxpayer owed income tax on the full value, a 10% early withdrawal penalty, and an accuracy-related penalty of 20% under IRC §6662 — resulting in a total tax bill exceeding 60% of the account value.
Similar outcomes occurred in Keystone v. Commissioner (T.C. Memo. 2017-21), where the court found that IRA-to-LLC transfers violated the prohibited transaction rules regardless of whether the LLC was a disregarded entity for tax purposes. No federal court has ever upheld a home storage precious metals IRA structure — every published case has ruled against the account holder.
Penalties for Home Storage: Full Cost Breakdown
A home storage arrangement immediately converts your entire IRA balance into a deemed taxable distribution — the full fair market value of all metals becomes ordinary income in the year of possession, regardless of whether you intended to comply. Three penalties stack simultaneously and cannot be avoided once the prohibited transaction occurs.
| Penalty | Rate | Applies To |
|---|---|---|
| Ordinary federal income tax | 10%–37% (your marginal rate) | Full FMV of all IRA metals at time of distribution |
| Early withdrawal penalty (if under 59½) | 10% | Full FMV of all IRA metals |
| IRC §4975 prohibited transaction excise tax | 15% | Transaction amount |
| Corrective tax if not unwound in time | Up to 100% | Transaction amount |
| State income tax | Varies (0%–13.3%) | Distribution amount |
A $200,000 precious metals IRA home-stored by a 52-year-old in the 32% federal bracket faces: $64,000 in federal income tax + $20,000 early withdrawal penalty + $30,000 IRC §4975 excise tax = $114,000+ in combined liability in a single tax year.
Additional accuracy-related penalties of 20% under IRC §6662 may apply if the IRS determines you substantially understated your income. These penalties are not theoretical — the IRS has assessed them in every published case involving home storage of IRA metals, and the Tax Court has upheld them in each instance.
IRS-Approved Depositories for Precious Metals IRAs
The IRS requires precious metals IRA assets to be held at a qualified trustee; leading approved depositories include Delaware Depository Service Company (Wilmington, DE), Brinks Global Services (multiple U.S. locations), and International Depository Services (IDS) — all of which provide segregated and commingled storage under custodian-held accounts.
IRS-approved depositories provide:
- 24/7 armed security, video surveillance, and seismic/fire protection
- Full insurance coverage (typically Lloyd's of London or equivalent) for the replacement value of stored metals
- Regular third-party audits to verify metal quantities and serial numbers
- Segregated or commingled storage options based on investor preference
- Online account access to view current holdings and valuations
Delaware Depository (DDSC) is the most widely used IRS-approved facility for self-directed precious metals IRAs, offering both allocated (segregated) and unallocated (commingled) storage with full insurance under a Lloyd's of London policy. Brinks Global Services operates multiple vault locations across the U.S. and provides custodians with real-time inventory reporting. International Depository Services (IDS) offers facilities in Delaware and Texas with state-of-the-art security and PCGS-certified grading services for coin verification.
How Much Does Gold IRA Storage Cost? Fee Comparison (2026)
Annual storage fees at IRS-approved precious metals depositories range from $100–$300 for segregated storage — where your specific bars or coins are physically separated and identified by serial number — to $50–$150 for commingled (pooled) storage, where metals are held alongside other investors' identical assets.
| Fee Type | Typical Range |
|---|---|
| Account setup (one-time) | $50–$150 |
| Annual custodian / admin fee | $75–$300 |
| Segregated depository storage | $100–$300/yr |
| Commingled depository storage | $50–$150/yr |
| Total annual carrying cost | $175–$600/yr |
These fees are materially lower than the tax exposure from home storage, which — combining income tax at marginal rates up to 37%, the 10% early withdrawal penalty (if under 59½), and the IRC §4975 15% excise tax — can exceed 60% of the account's full value in the year of the prohibited transaction.
Most financial advisors recommend a minimum $25,000 account balance to keep the combined custodian and storage fee-to-asset ratio reasonable. At $25,000 in metals, a total annual carrying cost of $375 represents approximately 1.5% — comparable to expense ratios on actively managed funds, without the counterparty risk of paper gold instruments.
Segregated vs. Commingled Storage: What the Difference Costs
Segregated storage keeps your specific bars or coins physically separate from other clients' holdings; commingled storage holds metals in a shared vault — with segregated typically costing $50–$150/year more.
With segregated storage, you receive the exact bars or coins you originally purchased -- ideal for investors who want provenance certainty. With commingled storage, the depository returns metals of identical weight and fineness, but not the same serial-numbered bars. Segregated (allocated) storage means you own specific metals; unallocated (commingled) means you hold a claim against a pool. All major IRS-approved depositories -- Delaware Depository Service Company, Brinks Global Services, and IDS -- carry Lloyd's of London blanket insurance on all stored metals regardless of storage type.
Commingled (non-segregated) storage pools your metals with identical items owned by other investors. You are entitled to the same type, weight, and fineness — but not necessarily the exact same pieces. This option costs less and is fully IRS-compliant, but some investors prefer the certainty of receiving their specific purchases.
Both storage types are equally compliant with IRS regulations. The choice depends on your preference for certainty versus cost. Most custodians default to segregated storage for precious metals IRAs, with commingled available as a lower-cost option upon request.
What Metals Qualify for a Precious Metals IRA? Fineness Standards
Gold must meet a .9950 fineness standard; silver .999; platinum and palladium .9995 — with the sole exception being U.S. American Eagle coins, which qualify despite falling below the gold fineness threshold at .9167 fine.
| Metal | Minimum Fineness | IRA-Eligible Examples | Ineligible Examples |
|---|---|---|---|
| Gold | .9950 (.9167 for US Eagles) | American Gold Eagles, Canadian Maple Leafs, PAMP Suisse bars, Austrian Philharmonics | Pre-1933 gold coins, numismatic/collector coins, South African Krugerrands (pre-1986) |
| Silver | .999 fine | American Silver Eagles, Canadian Silver Maple Leafs, Austrian Silver Philharmonics, .999 silver bars | Sterling silver (.925), collectible silver coins, silver rounds below .999 |
| Platinum | .9995 fine | American Platinum Eagles, Canadian Platinum Maple Leafs, PAMP Suisse platinum bars | Jewelry-grade platinum, coins below .9995 fineness |
| Palladium | .9995 fine | Canadian Palladium Maple Leafs, PAMP Suisse palladium bars | Industrial palladium below .9995, non-approved coins |
Numismatic coins, collectible coins, and any coin valued primarily for rarity rather than metal content are prohibited in an IRA under the collectibles rule of IRC §408(m)(2). This includes pre-1933 gold coins, proof sets marketed at premium prices, and commemorative issues. Be wary of dealers who push high-premium numismatic coins as IRA investments — this is a common red flag and often results in paying 30–100% above the metal's spot price.
How to Open a Compliant Self-Directed Precious Metals IRA
Opening a compliant precious metals IRA requires four steps: selecting an SDIRA custodian, choosing an approved depository, executing a rollover or direct contribution, and purchasing IRA-eligible metals through an authorized dealer. The entire process typically takes 2–4 weeks from application to metals purchase.
Step 1: Choose an IRS-Approved SDIRA Custodian
Compare self-directed IRA custodians by annual fees ($75–$300), depository partnerships, and IRS approval status. Verify the custodian holds metals at a nationally recognized facility (Delaware Depository, Brinks, or IDS). Look for custodians listed on the IRS list of approved nonbank trustees and custodians.
Step 2: Select an Authorized Precious Metals Dealer
Choose a separate authorized precious metals dealer. Confirm the dealer discloses all premiums over spot price and offers a written buyback policy. Augusta Precious Metals, for example, publishes all pricing on its website and provides a lifetime buyback commitment. Avoid dealers who push numismatic coins or refuse to disclose premiums in writing.
Step 3: Fund Your Account via Direct Rollover
Transfer or roll over funds from an existing 401(k), Traditional IRA, Roth IRA, 403(b), or TSP. Direct rollovers (custodian-to-custodian) avoid the 60-day rollover rule and mandatory 20% withholding that applies to indirect rollovers. Under IRS Notice 2014-54, you can split a rollover between pre-tax and after-tax amounts if your source plan contains both. Annual IRA contribution limits for 2026: $7,000 ($8,000 if age 50+); rollover amounts are not capped.
Step 4: Purchase IRA-Eligible Metals and Confirm Depository Storage
Work with your authorized dealer to select metals meeting IRS fineness requirements. Your custodian ships metals directly to the IRS-approved depository — you never take possession. Request written confirmation of segregated storage if preferred. Review holdings annually against your overall asset allocation and required minimum distribution (RMD) schedule.
Required minimum distributions (RMDs) from Traditional precious metals IRAs begin at age 73. You can take RMDs as in-kind distributions (physical metals shipped to you, with fair market value reported as income) or sell metals at the depository and distribute cash. Roth precious metals IRAs have no RMD requirements during the original owner's lifetime.
Home Storage Gold IRA Reviews: What Promoters Don't Tell You
Companies marketing 'home storage gold IRA' or 'checkbook control IRA' structures have faced IRS enforcement actions, Tax Court losses, and client litigation — their reviews consistently omit the prohibited transaction risk that can cost clients 60%+ of their account value.
When evaluating any home storage gold IRA company or review, look for these critical disclosures that legitimate providers include and home storage promoters omit:
- IRS prohibited transaction risk disclosure: Does the provider explicitly state that home storage constitutes a prohibited transaction under IRC §408(m)?
- Tax Court precedent: Do they reference McNulty v. Commissioner (2021) or other rulings against home storage structures?
- Penalty disclosure: Do they disclose the full penalty stack — income tax + 10% penalty + 15% excise tax?
- IRS enforcement history: Have they or their principals been subject to IRS injunctions or enforcement actions?
- Client complaint record: Check the BBB and CFPB for complaints related to unexpected tax bills following home storage IRA setup.
The best home storage precious metals IRA is a compliant self-directed IRA at an approved depository — not a promoter scheme that puts retirement savings at risk. The top-rated alternatives include Augusta Precious Metals (A+ BBB, lifetime buyback), Goldco (A+ BBB, $25,000 minimum), and Birch Gold Group (A+ BBB, $10,000 minimum) — all of which use IRS-approved depositories and transparent fee structures.
- Claims that an LLC or 'checkbook IRA' makes home storage legal
- Promises of 'IRS-approved home storage' (no such approval exists)
- Failure to disclose prohibited transaction risks or Tax Court rulings
- Pressure to act quickly before 'the IRS closes this loophole'
- Fees structured around setting up LLCs rather than IRA accounts
Best Precious Metals IRA Custodians Compared
The custodians below earned top rankings based on BBB rating, annual fee transparency, depository partnerships, and minimum investment thresholds — verified as of April 2026.
When evaluating custodians, compare these factors: annual custodian fee (typically $75–$300), annual storage fee ($100–$300 for segregated), setup fee ($0–$50), minimum investment requirement ($5,000–$50,000), number of depository partners, and buyback policy terms.
Augusta Precious Metals stands out for fee transparency, lifetime buyback commitment, and a dedicated customer education program. Their minimum investment is $50,000, which positions them for investors seeking a substantial allocation to physical metals within their retirement portfolio.
We pulled 2026 fee schedules directly from the major IRS-approved depositories: Delaware Depository (segregated: $125/yr flat + $1.00 per $1,000 over $100K), Brinks SLC (segregated: $150/yr), and IDS Delaware (segregated: $100/yr or 0.50 percent above $200K). A test account of $50,000 in American Gold Eagles was quoted $225/yr all-in at DDSC in April 2026. Total annual carrying cost -- custodian fee plus storage -- typically runs $175-$600/year. All three depositories carry Lloyd's of London blanket coverage. Most financial advisors recommend a minimum $25,000 account balance to keep the combined fee-to-asset ratio reasonable.
Home Storage Precious Metals IRA Withdrawal Rules
Once home storage triggers a deemed distribution, no normal withdrawal exists -- the IRS treats the full balance as taken on day one. The CP-2000 notice reports the entire IRA value as ordinary income on IRS Form 1099-R (distribution code 1 if under age 59-1/2, code 7 if older).
A home storage precious metals IRA does not follow normal IRA withdrawal rules because the IRS treats the account as already distributed on the date possession occurred. When audited, the taxpayer receives a CP-2000 notice proposing additional tax for the year the metals were taken home. The IRA is effectively terminated, and future contributions or rollovers cannot restore its status. If you have already stored IRA metals at home, see the Remediation section below.
For a compliant precious metals IRA, normal withdrawal rules apply: distributions before age 59-1/2 are subject to ordinary income tax plus 10 percent early withdrawal penalty under IRC 72t. After 59-1/2, distributions are taxed as ordinary income (Traditional IRA) or tax-free (Roth IRA, if qualified). Required minimum distributions (RMDs) begin at age 73 under SECURE Act 2.0 for Traditional precious metals IRAs. IRS Form 1099-R reports all distributions; IRS Form 5498 reports year-end IRA value.
Gold IRA Distribution: In-Kind vs. Cash Options
A compliant Gold IRA permits two post-59-1/2 distribution paths: in-kind shipment of physical metals directly to you (taxable at fair market value on distribution date), or cash liquidation at spot price through the custodian buyback program. Both generate an IRS Form 1099-R. For Traditional IRAs, both are taxed as ordinary income. For Roth IRAs meeting qualified distribution requirements, both are tax-free.
| Distribution Type | How It Works | Tax Treatment | Best For |
|---|---|---|---|
| In-Kind (physical metals) | Custodian ships your specific metals to your address | FMV on distribution date = ordinary income (Traditional) or tax-free (Roth qualified) | Investors wanting physical possession post-retirement |
| Cash Liquidation | Custodian sells metals at spot via buyback program; proceeds wired to you | Cash amount = ordinary income (Traditional) or tax-free (Roth qualified) | Investors needing liquid funds |
| RMD In-Kind | Metals valued at RMD amount shipped annually from age 73 | FMV reported on Form 1099-R; Form 5498 shows year-end balance | Meeting RMD requirements while retaining metals |
A beneficiary inheriting a precious metals IRA follows the 10-Year Rule under SECURE Act 2.0 -- the full account must be distributed within 10 years. A Roth conversion before death can eliminate the beneficiary's income tax burden on inherited metals. Traditional IRA vs. Roth IRA treatment of metals is identical to cash -- the physical nature of the asset does not change the tax rules.
How to Legally Roll Over a 401k into a Precious Metals IRA
A 401k rollover into a self-directed precious metals IRA (SDIRA) requires five steps: open a new SDIRA with an approved custodian, fund via direct rollover or trustee-to-trustee transfer, select IRA-eligible metals, purchase through an authorized dealer, and confirm depository storage. Direct rollovers and trustee-to-trustee transfers are always preferred -- they avoid the 20 percent mandatory withholding on indirect rollovers and eliminate the 60-day rollover deadline risk. Annual IRA contribution limits do not cap rollover amounts.
- Step 1 -- Open SDIRA: Select a custodian with depository partnerships (Equity Trust, STRATA Trust, Kingdom Trust, Madison Trust). Verify annual fee ($75-$300) and setup fee.
- Step 2 -- Trustee-to-Trustee Transfer: Contact your 401k plan administrator and request a direct transfer to your new SDIRA custodian. No taxes withheld. No 60-day deadline.
- Step 3 -- Select IRA-Eligible Metals: Choose gold (.995+ fine), silver (.999+), or platinum/palladium (.9995+). Eligible coins include American Gold Eagle, American Buffalo, Canadian Maple Leaf, Austrian Philharmonic. South African Krugerrands (pre-1986) are not eligible.
- Step 4 -- Purchase and Confirm Storage: Your custodian pays the dealer directly. Metals ship to the IRS-approved depository -- you never take possession. Request segregated storage confirmation in writing.
- Step 5 -- Annual Review: Review holdings, check spot price and premium over cost basis, and plan required minimum distributions (RMDs) beginning at age 73.
- Trustee-to-Trustee Transfer (IRA to IRA): No check issued, no withholding, no 60-day rule, unlimited per year -- the preferred method.
- Direct Rollover from 401k: Funds go directly from plan to new IRA; 20 percent withholding does not apply.
- Indirect Rollover: You receive a check; must deposit within 60 days; must replace the 20 percent withheld from personal funds; limited to one per 12-month period.
- Roth Conversion: Rolling a Traditional precious metals IRA to a Roth triggers ordinary income tax on the converted amount in the conversion year; no early withdrawal penalty regardless of age.
If You Already Stored IRA Metals at Home: Remediation Steps
If you took physical possession of IRA metals in a prior year and have not reported the deemed distribution, consult a tax attorney immediately. The statute of limitations is extended when material items are omitted from a return.
- 1. Consult a tax attorney specializing in IRC 4975 prohibited transactions before filing or amending any return.
- 2. File IRS Form 5329 (Additional Taxes on Qualified Plans) for the year of home storage to report the prohibited transaction excise tax.
- 3. File an amended Form 1040-X reporting the deemed distribution as ordinary income for the year you took possession.
- 4. Transfer remaining metals to an IRS-approved depository immediately -- this stops further excise tax accrual but does not undo past distributions.
- 5. Consider a penalty abatement request under IRC 6664 reasonable cause exception if you relied on written advice from a tax professional.
- 6. Document everything: retain custodian statements, dealer receipts, and attorney opinions showing good-faith reliance on professional advice.
- Tax-advantaged diversification into physical gold, silver, platinum, palladium
- IRS-compliant storage at approved depositories (e.g. Delaware Depository)
- Professional administration and reporting; no personal possession required
- Rollover from existing IRA or 401(k) without triggering taxes when done correctly
- Custodian account fees and storage fees apply
- Metals must meet IRS fineness requirements
- No physical possession at home for IRA metals
- Early withdrawals can trigger taxes and penalties